Business Tax Consultant: How Professional Guidance May Help Navigate Complex Tax Rules

Strategic tax planning, deductions, and documentation methods
Strategic planning discussions with consultants often revolve around timing, classification, and documentation of transactions that affect taxable income. Advisors may describe how acceleration or deferral of income and expenses can change tax reporting periods and the potential impact on financial statements. They also typically explain common deduction categories—such as employee compensation, operating expenses, and capital expenditures—and the types of records that support each category. This information is designed to inform decision-making and to clarify documentation practices relevant to specific tax provisions.
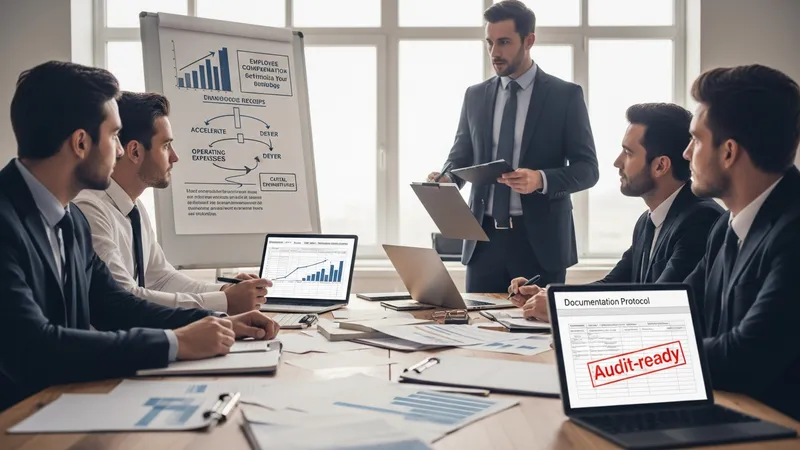
Consultants frequently review documentation protocols that support deductible items, such as maintaining contemporaneous records for travel or business entertainment where relevant tax rules apply. They may provide templates or checklists that identify the key data points typically considered relevant by tax authorities. These materials aim to make it easier for internal staff to collect and retain evidence that aligns with standard administrative expectations. The intent is educational: to increase the reliability of deductions claimed based on available facts.
When multiple tax treatments are possible, consultants may present comparative analyses that describe potential tax consequences under different classifications. For example, they might outline how treating a payment as capital expenditure versus repair expense can affect depreciation schedules and current-year deductions. Such analyses are framed quantitatively where possible and typically include assumptions, so readers can assess which factors most influence the results. This approach helps organizations weigh accounting and tax trade-offs within their operational context.
Consultants often highlight record retention timelines and indexes that help locate supporting documents if needed later. They may describe how consistent classification in accounting systems reduces ambiguity and simplifies subsequent tax reporting or audits. These procedural recommendations typically aim to integrate tax documentation needs into regular operational routines so that reporting teams have the materials required to substantiate positions without relying on ad hoc reconstruction of facts.