Energy Transition Investment: Key Strategies For Financing Low-Carbon Infrastructure

Risk Assessment and Allocation in Energy Transition Investment
Risk assessment typically begins with identification of technical, commercial, and regulatory exposures. Technical risk covers construction timelines, technology performance, and integration with grid systems; commercial risk addresses demand, price volatility, and counterparty creditworthiness; regulatory risk includes permitting, tariff changes, and policy shifts. Quantitative risk matrices and scenario modelling are often used to estimate potential impacts on cash flow and debt service coverage, with sensitivity analyses to test key assumptions under different market conditions.
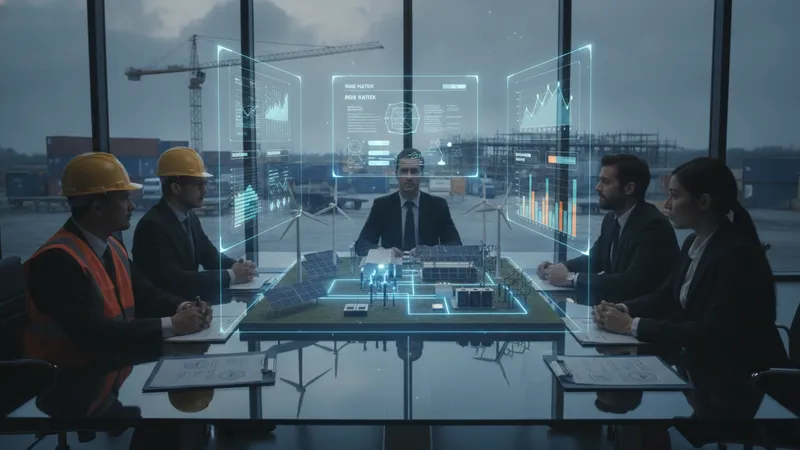
Contractual allocation of risks commonly uses instruments such as PPAs, construction contracts with liquidated damages, operation and maintenance agreements, and insurance. Power purchase agreements can transfer market risk to a counterparty if structured with fixed payments, while merchant exposure may remain where projects sell into spot markets. Construction contracts that include performance guarantees and milestone-based payments can reduce construction and commissioning uncertainties, though they may not remove all residual risks tied to supply chains or workforce availability.
Third-party risk mitigation tools are often used to enhance bankability. Political risk insurance, partial credit guarantees, and foreign exchange hedges can be relevant for projects exposed to currency or sovereign risks. Hedging instruments may cover commodity price exposure or interest rate risk on floating-rate debt. Lenders may require escrow accounts, debt service reserve funds, or sponsor support agreements to provide additional buffers against temporary revenue interruptions or cost overruns.
Due diligence often integrates technical reviews, environmental and social impact assessments, and legal reviews that verify contract enforceability and permitting status. Financial modelling commonly includes base-case and stress-case scenarios to examine debt service coverage ratios, equity internal rates of return under varied conditions, and covenant breach triggers. These practices typically inform negotiations over pricing, covenants, and triggers rather than offering assurances of future performance.