Auto Insurance: Introduction To Comparing Features Across Multiple Policy Options

Optional benefits, endorsements, and policy terms affecting selection
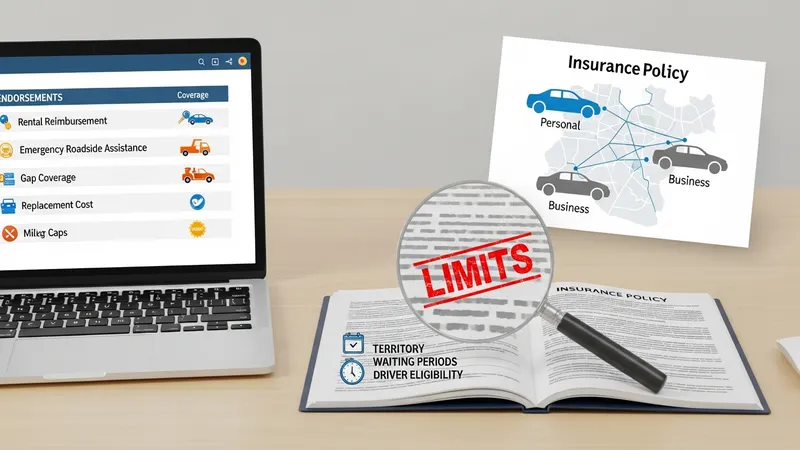
Optional benefits and endorsements expand coverage scope and often address specific needs not covered by standard policies. Examples include rental reimbursement, emergency roadside assistance, gap coverage that addresses loan or lease shortfalls, and replacement cost for totaled vehicles. The availability, cost, and precise terms of these endorsements can vary significantly, so inclusion in a comparative matrix helps identify differences. It is useful to examine waiting periods, claim documentation requirements, and any mileage or usage limits associated with these options.
Policy terms relating to territory, permitted use, and driver eligibility commonly influence comparative outcomes. For example, some policies restrict coverage to non-commercial personal driving, while others may provide specific endorsements for business use of a personal vehicle. Territory clauses can affect coverage when traveling or temporarily relocating. When comparing policies, document any limitations on named drivers, household members, or permissive users, since these classifications determine who is covered in a loss scenario.
Loss settlement methods and repair standards are additional operational details that often appear in endorsements. Policies may specify actual cash value settlements, stated value agreements, or replacement cost provisions, each of which affects post-loss financial outcomes. Repair standards — such as use of original equipment manufacturer parts versus aftermarket parts — and whether the insurer offers direct repair networks influence repair quality and timelines. These practical terms should be recorded when comparing optional endorsements across multiple policies.
Finally, consider premium payment plans, grace periods, and surcharge or renewal rating practices as components of selection. Some insurers offer installment payment options with administrative fees, while others may apply different credit or driving history factors at renewal. Understanding these administrative and billing terms helps to align expectations about ongoing costs and policy stability. Summarizing these contractual and operational distinctions alongside core coverage features yields a more comprehensive comparative picture.